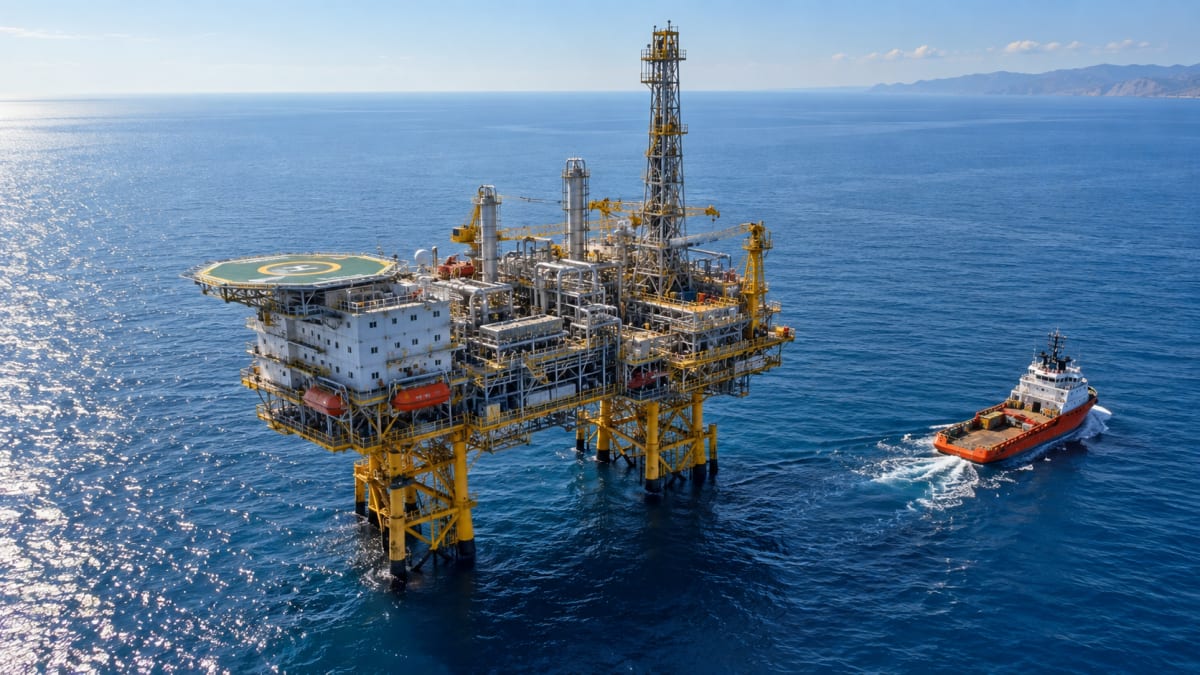
Energean has entered exclusive talks to buy a package of bp's Egyptian oil and gas assets, a deal that could raise around $1 billion for the British major. The package covers bp's interests in the producing West Nile Delta gas assets, held with Harbour Energy, and its 50% contractor working interest in the Temsah concession in the eastern Mediterranean. Temsah has grown more valuable since Eni's Denise West discovery this year, estimated at some 2 trillion cu ft of gas. bp would keep its Egyptian assets held through Arcius Energy, its joint venture with Abu Dhabi's XRG, including the giant Zohr field. For Energean, the purchase would deepen its Egyptian position and reduce dependence on its Israeli gas operations, which have seen repeated shutdowns during regional conflict.
What changes when a major hands assets to an independent
Not the hardware. The platforms, the subsea equipment, the compressors and the processing trains are all exactly where they were the day before. What changes is the organisation responsible for them, and that reaches rotating equipment faster than most people expect.
Majors run central engineering; independents run lean. A company of bp's size maintains in-house specialist functions: rotating equipment engineers, corporate specifications, standardised machine types across a global fleet, framework agreements with manufacturers. An independent typically cannot justify that overhead. The expertise shifts toward vendors and contractors, and the operator's job becomes managing them well rather than doing it directly.
Spares strategy changes with fleet size. Standardising on a handful of pump and compressor models across dozens of assets lets a major pool spares globally, so one spare rotor serves several fields. Take a few assets out of that fleet and the new owner loses access to the pool. Whether critical spares transfer with the deal, and on what terms, is a genuinely important commercial question that rarely reaches the headlines.
Decision speed cuts both ways. Independents often approve work faster, with fewer approval layers, and the assets are core to them rather than one line in a global portfolio. Assets that were marginal to a major and starved of capital frequently see more investment after a sale, not less. That is much of the logic behind these transactions.
The strategic point is about risk, not geology. Energean's Israeli operations have been repeatedly interrupted by conflict. Buying producing Egyptian gas spreads that exposure across a second country and a second set of infrastructure. This is portfolio engineering rather than reservoir engineering.
The deal is exclusive talks, not a signature, and these can still fall apart. But the pattern is now well established: majors concentrating on their largest positions, independents buying the assets that no longer fit.